First-Time Homebuyer Loans
Buying your first home is a significant financial milestone. We provide the professional guidance and loan options necessary to help you work through the process with clarity and confidence, from your initial pre-approval to the day you receive your keys.
With a Bank of Utah Home Loan, You Can:
Start with Strategy
We explain each phase of the process clearly, so you’re prepared for every milestone from first conversation to closing.
Professional Advocacy
Our loan officers prioritize your long-term financial health, offering personalized advice to help you make informed decisions.
Tailored Loan Options
We review your budget and goals to match you with the loan program — such as FHA, VA, USDA or conventional — that fits best.
FHA = Federal Housing Administration • VA = Veterans Affairs • USDA = Department of Agriculture
What Could Your Monthly Mortgage Payment Look Like?
Start with a home price and the amount you plan to put down. Then adjust the interest rate and loan term to see how different choices could affect your estimated monthly payment.
Open Advanced options to review and adjust the estimates for property taxes, homeowners insurance and private mortgage insurance (PMI). Preset amounts are for planning purposes and may differ from your actual costs.
Ready to Talk Through Your Numbers?
A loan officer can help you understand how your estimated payment fits your budget, compare loan options and determine what you may qualify for. You don’t need to have every detail figured out to get started.
Find a Loan OfficerDisclosure: This tool is for estimation and informational purposes only. Results are based on the inputs provided and do not constitute a commitment to lend, rate lock or formal pre-approval. Actual loan terms, payments and eligibility depend on a complete credit review, income verification and property appraisal. Review the calculator’s payment breakdown to see which costs are included. HOA fees, other assessments and upfront costs such as closing costs may be additional. Any preset interest rate is for illustration and is not a Bank of Utah rate quote. All loans subject to credit approval.
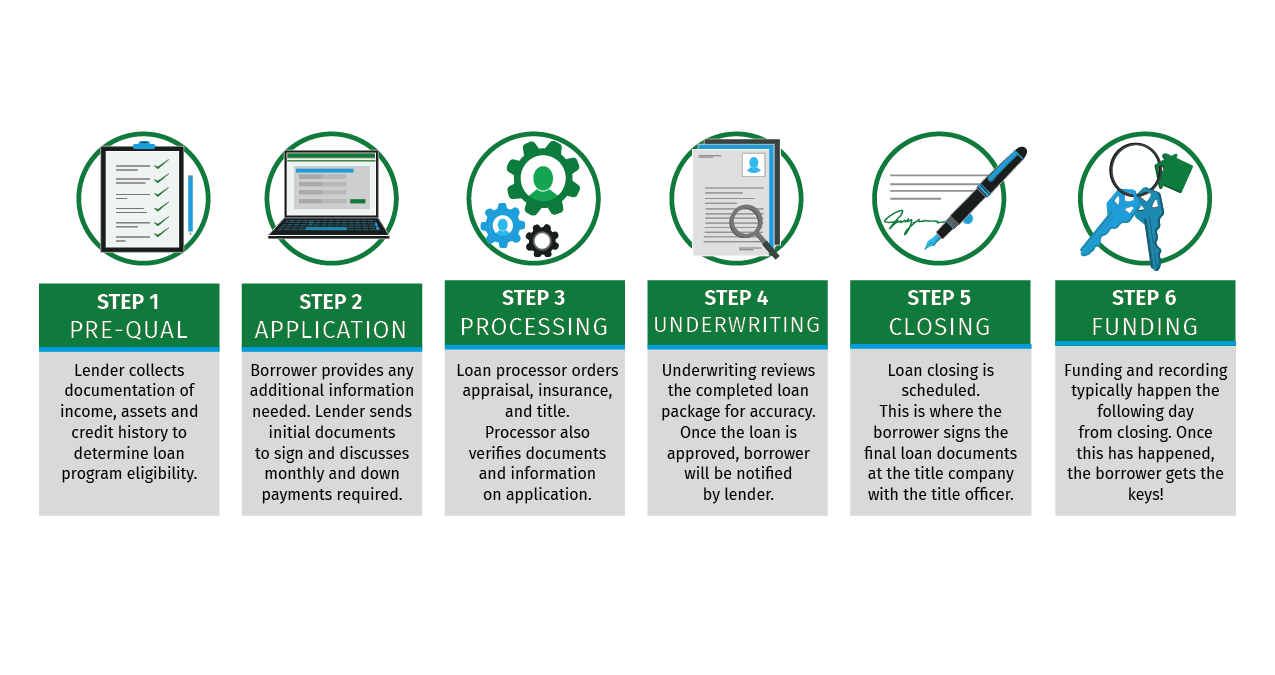
The Mortgage Process at a Glance
Understanding the sequence of a home loan helps you feel prepared for each stage.
Which Loan Program Is Right for You?
Every homebuyer’s financial picture is unique. Here’s how we commonly match buyers with the right loan program.
Starting with smaller savings?
A Federal Housing Administration (FHA) loan offers flexible credit requirements and down payments as low as 3.5 percent, making it a strong starting option for first-time buyers.
Have established credit?
A conventional loan offers long-term flexibility. It’s a strong fit if you have solid credit and want the option to cancel private mortgage insurance once you reach 20 percent equity.
Served in the military?
A Veterans Affairs (VA) loan recognizes your service with meaningful benefits, including potential options like zero down and no monthly mortgage insurance.
Buying in a qualifying area?
A U.S. Department of Agriculture (USDA) loan can be a strong zero-down option in designated rural or developing areas. Many Utah communities qualify based on location and income.
Self-employed or alternative income?
Non-qualified mortgage (non-QM) loans offer flexible financing options tailored for self-employed buyers, real estate investors and non-traditional income streams.
Explore Homebuyer Assistance Options
Utah Housing Corporation and other partners offer homebuyer assistance programs that can help with upfront costs such as down payment or closing expenses. In some cases, assistance may be available for up to $20,000, depending on the program and eligibility.
Connect With a Loan OfficerPrograms are administered by Utah Housing Corporation and other agencies. Income, purchase price and other limits apply.
Frequently Asked Questions
Talk With Us About Your Next Step
Have questions or want to walk through your options? Connect with a loan officer or start your application online when it works for you.
All loans subject to credit and underwriting approval, additional terms and conditions apply. Specific eligibility requirements exist for down payment assistance, FHA, VA, and USDA programs.